Sattva Ekatra Plot Loan Banks and Eligibility
Featured Image of Sattva Ekatra Plot Loan Banks and Eligibility


Sattva Ekatra plot loan can be applied through major banks and housing finance companies after project document checks and buyer eligibility checks. Banks usually fund 70% to 75% of the plot value for approved plotted developments. The buyer has to pay the balance amount from personal funds.

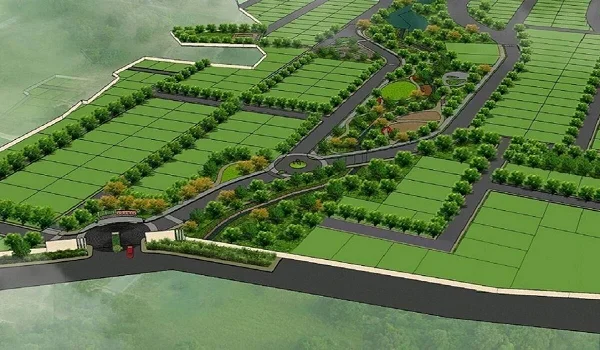
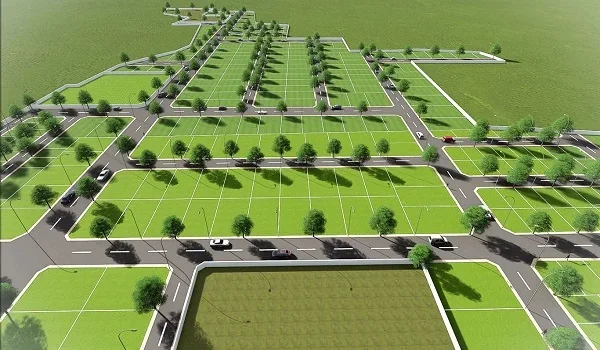
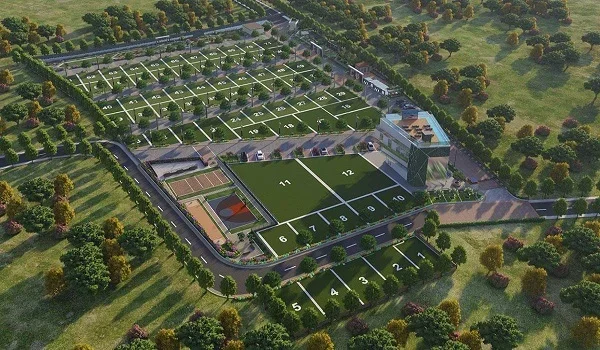
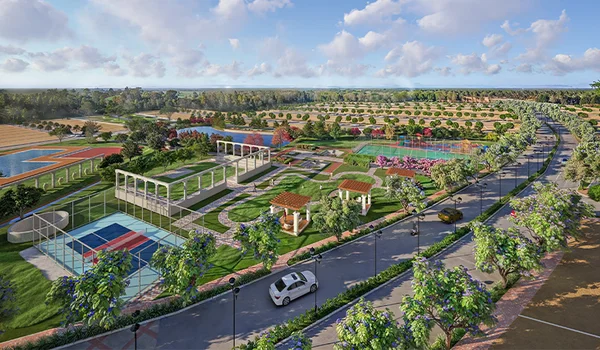
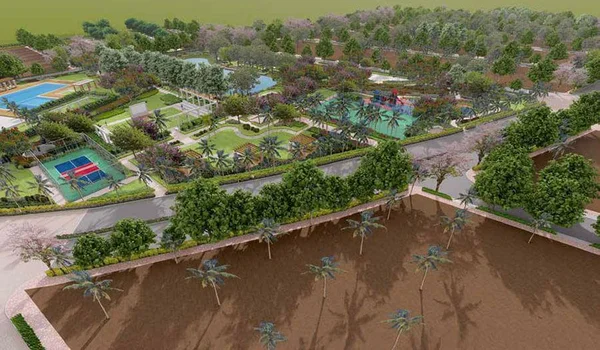
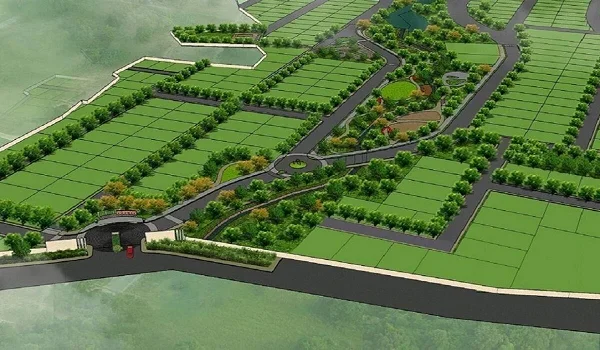
Sattva Ekatra is a RERA-approved plotted development at Thippapura Village, near Doddaballapura in Bengaluru Rural. The project has 503 plots, including 502 residential plots and 1 commercial or CA plot. Plot sizes include 20x30, 30x40, 30x45, 30x50, 30x60 and odd-dimension plots. The RERA number is PRM/KA/RERA/1250/301/PR/180926/008945.
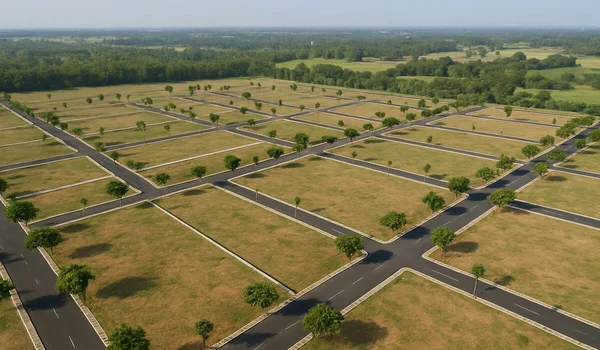
Sattva Ekatra Plot Loan Banks


Plot loans for Sattva Ekatra can be checked with leading banks and housing finance companies. The final loan approval depends on project approval, buyer income, credit score and plot documents.

Common plot loan options include:

  • SBI
  • HDFC Bank
  • ICICI Bank
  • Axis Bank
  • LIC Housing Finance
  • Bank of Baroda
  • Canara Bank
  • PNB Housing Finance
  • Tata Capital Housing Finance

Buyers should confirm the approved bank list from the Sattva Ekatra sales team before applying. A project may have bank approvals in stages. Some banks may approve only selected plot types or payment stages.

Sattva Ekatra Plot Loan Eligibility


Sattva Ekatra plot loan eligibility depends on the buyer’s income, age, credit score, job profile, existing loans and repayment capacity. Banks also check the project documents before giving final sanction.

Most banks prefer a CIBIL score of 750 or above. A lower score can reduce the loan amount or increase the interest rate. Stable income is also important. Salaried buyers should have regular salary credits. Self-employed buyers should have clear business income and tax filings.

The buyer should also have enough funds for margin money. If the bank funds 75%, the buyer must arrange the remaining 25% plus stamp duty, registration and other charges.

Loan Amount for Sattva Ekatra Plots


Banks usually do not fund the full plot price. For plotted developments, the loan amount is often around 70% to 75% of the property value. Some banks may offer a lower amount after valuation.

For example, if a Sattva Ekatra plot costs Rs. 1 crore, the bank may fund around Rs. 70 lakh to Rs. 75 lakh. The buyer may need to arrange Rs. 25 lakh to Rs. 30 lakh from personal funds. Extra charges like stamp duty and registration are usually paid separately by the buyer.

This is only an example. The final amount depends on bank policy, property value, buyer profile and project approval.

Sattva Ekatra Plot Price and Loan Planning


Sattva Ekatra has different plot sizes. The entry plot is 20x30, which is about 600 sq. ft. The larger regular plot is 30x60, which is about 1,800 sq. ft.

Indicative prices start from around Rs. 51.6 lakh for a 20x30 plot. A 30x40 plot is around Rs. 1.03 crore. A 30x50 plot is around Rs. 1.29 crore. A 30x60 plot is around Rs. 1.55 crore.

Loan planning should be done before booking. A buyer should check the EMI, down payment, registration charges and future construction cost. A plot loan only funds the land purchase. If the buyer wants to build a house later, a separate construction loan may be needed.

Documents Needed for Plot Loan


Banks ask for personal, income and property documents before approving a plot loan. The document list may change by bank and buyer type.

Common documents include:

  • PAN card
  • Aadhaar card
  • Address proof
  • Passport-size photo
  • Salary slips
  • Bank statements
  • Form 16 or ITR
  • Business proof for self-employed buyers
  • Booking form
  • Cost sheet
  • Allotment letter
  • RERA details
  • Approved layout plan
  • Sale agreement draft

NRI buyers may need a passport, visa copy, overseas address proof, NRE or NRO bank details and income proof from the country of residence.

Sattva Ekatra Project Documents Checked by Banks


Banks do not check only the buyer. They also check the project. For Sattva Ekatra, banks will review project approval, RERA number, layout plan, title documents, survey numbers and promoter details.

Sattva Ekatra is approved by Doddaballapur Planning Authority. The approved plan number is DPA/TP/LAO/30/25-26. The project is located at Survey Nos. 42, 43/1, 43/2, 44/1, 44/3, 45/1, 45/2, 46/1, 46/2, 46/3 and 47/1.

The promoter is Shirasa Construction Private Limited. The project is sold under the Sattva Group brand. These details should match the documents given to the bank.

Plot Loan vs Home Construction Loan


A plot loan is used to buy land. A home construction loan is used to build a house on the land. These are not the same.

For Sattva Ekatra, the first loan will be a plot loan if the buyer is buying only the site. Later, when the buyer wants to build a house, the bank may offer a construction loan. The construction loan may need an approved building plan, cost estimate and construction timeline.

Some banks also give composite loans. A composite loan covers both plot purchase and house construction. But the buyer may have to start construction within the bank’s allowed time.

EMI for Sattva Ekatra Plot Loan


Sattva Ekatra EMI depends on the loan amount, interest rate and tenure. A higher loan amount gives a higher EMI. A longer tenure can reduce EMI but increases total interest.

For example, a buyer taking a Rs. 75 lakh plot loan will have a higher EMI than a buyer taking a Rs. 40 lakh loan. The EMI also changes when interest rates change.

Before booking, buyers should ask the bank for an EMI estimate. They should also keep extra funds for registration, maintenance deposit, khata charges and future house construction.

Eligibility for Salaried Buyers


Salaried buyers can apply for a Sattva Ekatra plot loan if they have steady income and good repayment capacity. Banks usually check salary slips, bank statements, Form 16, company details and current loans.

A salaried buyer should keep the EMI within a safe limit. If there are already car loans, personal loans or credit card dues, the bank may reduce the plot loan amount.

A good CIBIL score, stable job and clean banking history can improve approval chances.

Eligibility for Self-Employed Buyers


Self-employed buyers can also apply for a plot loan. Banks will check ITR, GST returns, business bank statements, profit and loss statement and balance sheet.

The income should be stable. Sudden cash deposits or unclear income may delay approval. The bank may also ask for more documents if the business income is irregular.

Self-employed buyers should prepare documents before booking. This helps avoid delay after plot selection.

Sattva Ekatra Loan Process


The Sattva Ekatra loan process starts after plot selection. The buyer collects the cost sheet and booking details. Then the buyer applies for a plot loan with the chosen bank.

The bank checks the buyer profile first. After that, it checks project documents and plot papers. If both are approved, the bank gives sanction. Loan disbursal happens as per the payment schedule.

The usual process is:

  • Choose plot size and plot number
  • Collect cost sheet
  • Submit loan application
  • Give KYC and income documents
  • Bank checks project documents
  • Bank gives loan sanction
  • Buyer pays margin money
  • Bank releases payment as per demand

What Buyers Should Check Before Taking Loan


Buyers should check the full cost before taking a Sattva Ekatra plot loan. The plot price is only one part of the cost. Stamp duty, registration, legal charges, maintenance deposit and other charges should also be planned.

Buyers should also check whether prepayment is allowed. Many people close plot loans early when income improves. So prepayment rules matter.

The final loan should be comfortable. A plot is a long-term asset. The EMI should not disturb monthly expenses or future house construction plans.

FAQs


1. Can I get a bank loan for Sattva Ekatra plots?

Yes. Buyers can apply for a plot loan for Sattva Ekatra through banks or housing finance companies, subject to buyer eligibility and project approval.

2. Which banks give plot loans for Sattva Ekatra?

Buyers can check plot loans with SBI, HDFC Bank, ICICI Bank, Axis Bank, LIC Housing Finance, Bank of Baroda, Canara Bank and other lenders.

3. How much loan can I get for a Sattva Ekatra plot?

Most banks may fund around 70% to 75% of the plot value. The final amount depends on bank policy and buyer profile.

4. What CIBIL score is good for a plot loan?

A CIBIL score of 750 or above is usually better for plot loan approval.

5. What is the RERA number of Sattva Ekatra?

The RERA number is PRM/KA/RERA/1250/301/PR/180926/008945.
6. Is a plot loan the same as a home loan?
No. A plot loan is for buying land. A home construction loan is for building a house on the plot.

7. Can NRIs get a loan for Sattva Ekatra?

NRIs can apply for a plot loan if they meet bank rules and submit required documents.

8. What should I check before applying for a loan?

Check the plot price, down payment, EMI, interest rate, loan tenure, RERA number, approved plan, registration cost and bank approval status.

Sattva Ekatra Blog


Enquiry
Enquire Now